Sixty-three percent. That is the probability a bank in the lowest decile of fundamentals fails once a run hits it.
For a bank in the top decile, the same event is survivable to the point of near-irrelevance: strong banks, the New York Fed finds, "essentially never fail" when subject to a run.
The run is the same event in both cases. What differs is the balance sheet it lands on.
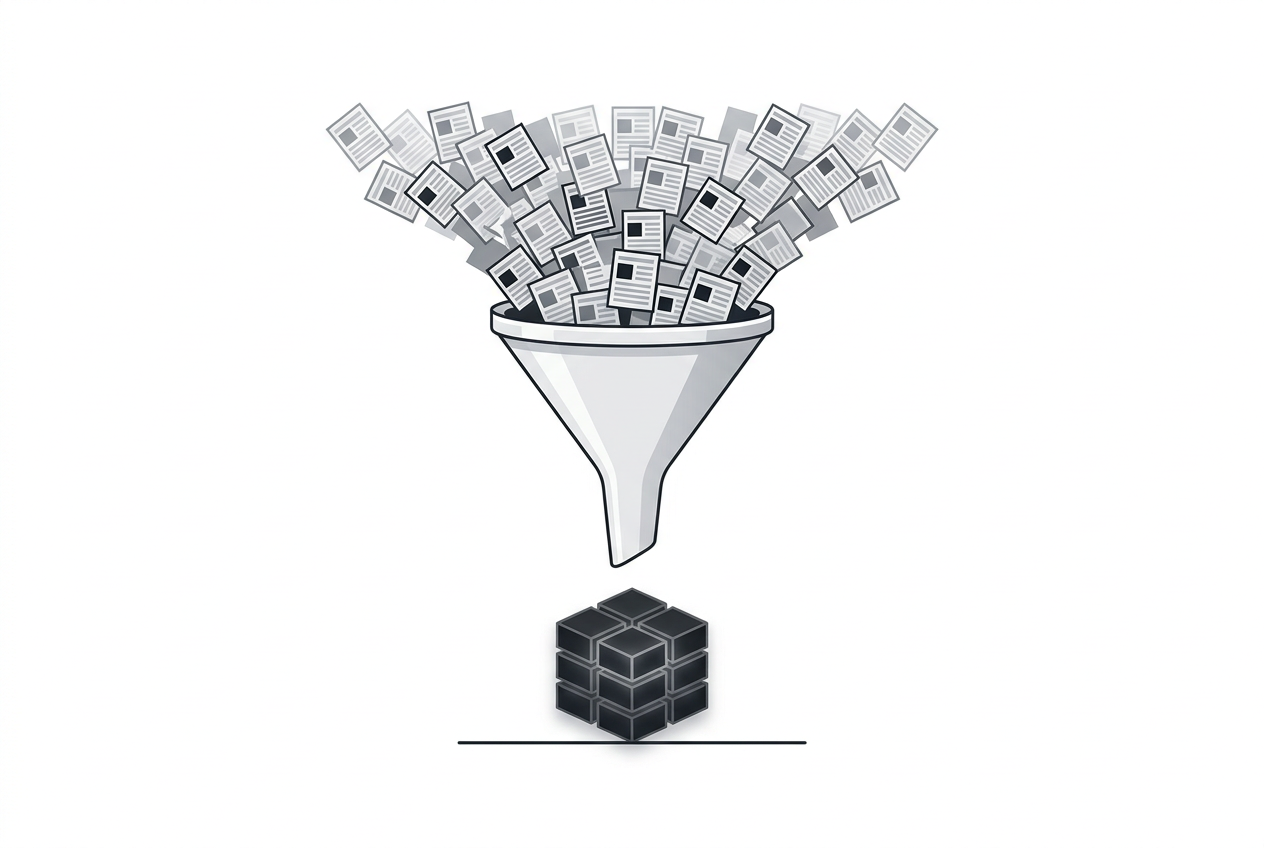
That single contrast is the payoff of a project that reads more like a machine-learning paper than a banking history. Researchers at the New York Fed, Richmond Fed, and MIT searched 374 million digitized newspaper articles and taught them to distinguish a depositor "clamoring for their money" from a ship that "runs into a riverbank" or a bank owner who "runs for office."
The point was to recover data that never existed in official form.
Regulators recorded when a bank closed its doors. They did not record the larger number of runs that a bank survived — episodes that left no regulatory trace precisely because the bank lived. History logged the deaths and lost the near-misses.
The pipeline narrowed those 374 million articles to roughly a million candidates by keyword, then handed each to multiple LLMs to parse the prose: which bank, what happened, was there a run, a suspension, a closure, a reopening, and how did the bank respond. The output is a database of more than 3,000 individual bank runs from 1863 to 1934, the National Banking Era through the Depression, though the underlying paper reports 4,049 runs on individual banks.
This week is about the framework for reading it — because the historical microdata reportedly tempers a longstanding argument that bears on which numbers you should be watching.
The argument is old. Do runs cause failures, or do failures cause runs?
Under the liquidity view, a wave of withdrawals forces fire-sale liquidation, and a self-fulfilling panic can sink an otherwise sound bank. Under the solvency view, losses erode equity first, and the run is merely the trigger that sets the timing of a closure already baked in.
The distinction is not academic. If runs are the root cause, the policy fix is plumbing — deposit insurance, lender of last resort. If insolvency is the root cause, the fix is capital, supervision, and risk management.
The new data lands hard on the solvency side.
Start with the Venn counts. Of the run episodes, 1,906 ended without failure and 1,515 ended with failure. The majority of runs do not kill the bank.
Read that against the base rate. A run raises the conditional probability of failure to 38 percent — enormous next to an unconditional annual failure probability of just 0.85 percent. A run is dangerous. It is not a death sentence.
What decides the outcome is fundamentals — capitalization, profitability, and reliance on cheap core deposits versus expensive noncore funding. Runs are more likely at weak banks to begin with, but the sharper result is what happens once a run occurs: 63 percent failure at the bottom decile, essentially zero at the top.
The survival mechanics are almost theatrical in the newspaper record. Strong banks fought runs by accommodating withdrawals and signaling strength — the classic move being to deliver a "truckload of cash" to the counter so depositors could see the money was there.
When that was not enough, owners injected fresh equity, borrowed from other banks, or invoked 30- and 60-day notice rules to slow withdrawals. In extreme cases they suspended convertibility entirely, usually paired with an examination to certify solvency. Clearinghouses show up explicitly in about 10 percent of runs.
Every one of these tactics buys a solvent bank time to sever illiquidity from insolvency. None of them saves an insolvent one; suspension there just leads to an examination that finds the hole and closes the bank.
That is the whole thesis in miniature. The truckload of cash works only if the books behind it are clean. Liquidity theater cannot manufacture solvency.
The truckload of cash works only if the books behind it are clean. Liquidity theater cannot manufacture solvency.
The recovery-rate evidence, per the separate Correia, Luck, and Verner work on "Bank Failures: The Roles of Solvency and Liquidity," reinforces it. Before federal deposit insurance in 1934, unsecured depositors of failed banks recovered only 66 cents on the dollar — assets fell well short of debts. Most failed banks were genuinely insolvent, not solvent victims of panic.
So the run is the trigger, not the gun. Which reframes the entire question of what to monitor now.
If fundamentals decide survival, you want a real-time read on fundamentals. In 1900 you did not have one — you found out via a run. In 2026 the closest thing we have is the coverage ratio: reserves banks set aside against credit losses, as a share of total loans.
And here is the number for the present tense. U.S. banks' coverage ratios held steady in the first quarter of 2026.
Steady is exactly the word to be careful with, because it is ambiguous in the specific way the historical data warns about.
One reading is benign. Coverage held flat because loan books are genuinely clean, expected losses are stable, and reserves match the risk. On this reading, the fundamentals that decide run outcomes are sound, and "steady" is a green light.
The other reading is the dangerous one. Coverage held flat because reserves are not being built ahead of losses that are accumulating off the visible balance sheet.
Coverage is backward-looking by construction. It reserves against what a bank recognizes. If the recognition lags the risk, a steady ratio is not a picture of health; it is a picture of a bank not yet marking the problem.
The historical lesson sharpens this. The banks that failed exhibited declining income, thinning capital, rising asset losses, and growing reliance on expensive funding — often after a stretch of rapid asset growth from aggressive lending. A flat coverage ratio through a period of aggressive credit expansion is precisely the pattern that precedes the deterioration.
Which is where the supervision question becomes load-bearing. The research reportedly says examiner assessments of asset quality — not run dynamics — help explain failures. Examiners were the ones who peered behind suspension and pronounced solvency or insolvency.
The coverage ratio is a summary statistic. It is only as informative as the loss recognition feeding it, and loss recognition is only as reliable as the supervision checking it.
So read the 2026 print for what it is. "Steady" tells you the number did not move. It does not tell you whether the books beneath it are clean or whether the reserves are simply lagging exposures no one has forced onto the balance sheet yet.
The 3,000 runs make the stakes concrete. The next run, whenever it comes, will not decide anything on its own. It will land on a balance sheet, and the balance sheet will decide.
Sixty-three percent or essentially zero. The coverage ratio is our best live guess at which side of that line a bank sits on — and steady is not the same as adequate.