Here is the contradiction most people are missing.
Nvidia's own executives insist their risk is "limited" because the compute they finance is "fungible and durable, and can be redeployed to support other customers." The bond market says the opposite. Nvidia carries Double A credit ratings, low debt, and $220 billion in projected profit this year — and its bonds still trade at spreads closer to a Triple B credit.
Both of those things cannot be true. Either the risk is contained, or the market is pricing a tail that Nvidia's balance sheet, on paper, should crush. The gap between the two is the whole story.
Either the risk is contained, or the market is pricing a tail that Nvidia's balance sheet, on paper, should crush. The gap is the whole story.
Start with the moment that should have been a slip and wasn't. On the August 26 earnings call, CFO Colette Kress said, "We know some will call this circular financing. We see it differently." Then she went further: "We expect them to become the largest technology companies in history."
Note what happened there. Nvidia named the objection before a single analyst raised it. That is not candor. That is a company that has war-gamed the criticism because it already understands the structure invites it.
The loop itself is simple to describe. Nvidia invests in an AI lab. The lab uses that money — or the credit Nvidia's involvement unlocks — to build a data center. The data center fills with Nvidia chips. That purchase books as Nvidia revenue. The share price and cash pile grow, and Nvidia invests again.
Kress told analysts that demand from labs Nvidia backs with its own balance sheet will contribute roughly a quarter of its business next year. A quarter of the revenue comes from customers whose ability to buy Nvidia depends on Nvidia.
The scale is now disclosed. Commitments and credit guarantees crossed $530 billion in July — more than triple the level three months earlier. Of that, $108.5 billion is credit guarantees, including a single $105 billion guarantee for an OpenAI data center being built by SB Energy.
Nvidia also lends its name in a second way. It promises to rent a slice of a smaller operator's capacity itself, which hands that operator's lenders a guaranteed income stream to lend against. Kress said Nvidia gets paid twice — once on the equipment, again on the rental.
So map the roles. Nvidia is the equity investor. Nvidia is the revenue recipient. Nvidia is the lender of name whose guarantee makes the debt bankable. Three distinct financial positions, one balance sheet.
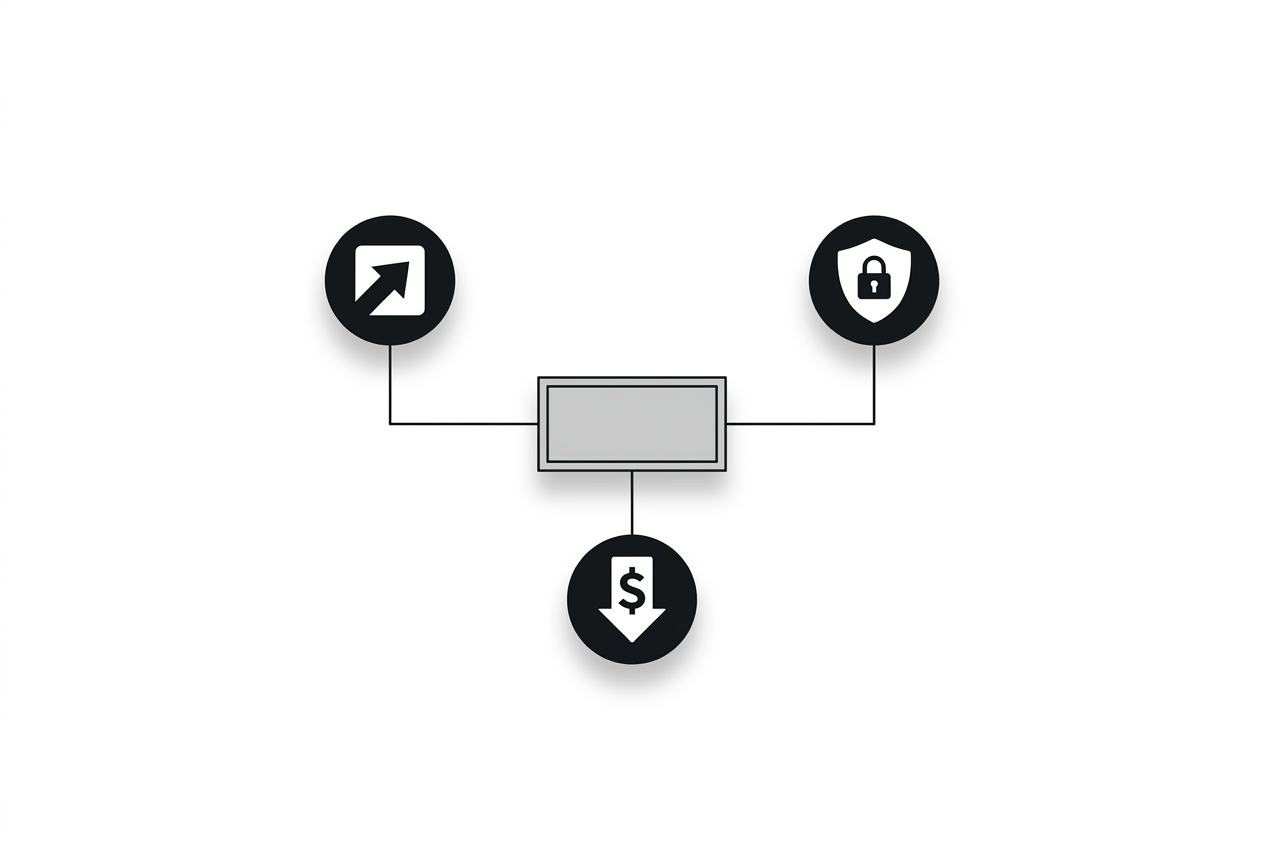
Morgan Stanley's credit analysts have a term for it: "balance-sheet-as-a-service." They wrote that Nvidia's financial strength is "increasingly turning the balance sheet into a strategic advantage — and part of the offering itself."
That is the elegant version. The blunt version is that the same entity is underwriting the demand it then records as sales.
And crucially, much of it is not yet real. The $500 billion in financing platforms with Apollo, BlackRock, Blackstone, Brookfield, Goldman and KKR remains a set of memoranda of understanding — non-binding. Nvidia's own results statement calls the partnerships "subject to definitive agreements." The $500 billion is an intention, not money in place.
This has happened before. Nvidia announced a flashy $100 billion deal with OpenAI late last year that first sparked the circular-financing fears — and it failed to materialize.
Now the turn. Into this structure lands a reported $13 billion bid for Hugging Face.
As a financial acquisition it makes no sense. Hugging Face generated roughly $150 million in annual revenue. That is about 86 times sales — for a company Nvidia tried to invest in last year at a $7 billion valuation, an offer Hugging Face rejected on principle.
Co-CEO Clem Delangue said in 2024, "Concentration of power is the biggest risk in AI!" The company that said that is now reportedly selling to the firm estimated to control 70 to 90 percent of AI chip sales.
Nvidia does not need the money. It projects 70 percent revenue growth next year at roughly 75 percent gross margins. So the price is not about revenue. It is about insurance.
Here is what the insurance protects against. The same week Nvidia reported doubled revenue, OpenAI published performance numbers for Jalapeño, its first custom inference chip, built with Cerebras — claiming higher throughput per watt and lower latency than Nvidia's GB200 and GB300 systems across public models like DeepSeek R1 and Kimi K2.5.
When BofA's Vivek Arya asked Jensen Huang how Nvidia squares financing labs that are designing chips to replace Nvidia, Huang's answer was that Nvidia sells a platform that works everywhere while rival chips are built for one service. His only regret, he said, was not investing more and sooner.
That is a supplier moat argument. And it is exactly the moat Jalapeño threatens. If the biggest buyers design their own inference silicon, the demand that feeds the loop starts leaking out the bottom.
This is why Hugging Face matters. The labs building custom chips will not sell those chips to anyone else. But the millions of developers who download open-weight models still need hardware to run them — and they can choose whose.
Own the on-ramp where models get downloaded and deployed, and you own the default. As one commenter put it bluntly, the play is "locking the next generation of programmers into CUDA."
So read the bid correctly. It is Nvidia telling you it already knows the supplier moat is eroding, and racing to build a distributional one before the erosion shows up in the numbers.
Which brings us to the concentration paradox at the center of all this.
Nvidia's entire defense rests on one sentence: if a customer fails, "the equipment can be moved to another buyer." Kress admits the catch herself — that claim "only holds while demand exceeds supply."
Demand exceeds supply today. But every load-bearing assumption in that sentence points the same direction. It holds only while lab valuations stay high and only while custom chips fail to land.
The moment either breaks, the fungibility defense breaks with it. If lab valuations correct, the buyer of last resort disappears exactly when you need it. If Jalapeño and its successors land, redeploying idled Nvidia gear competes against cheaper, better-suited silicon.
And in either scenario, it is the same company that wobbles across every role. The financier holds equity in falling labs. The supplier loses the chip sales. The guarantor is on the hook for guarantees like the $105 billion OpenAI backstop. The ecosystem owner has just paid 86 times revenue for a developer platform whose value assumed CUDA stayed dominant.
That is not diversification. That is the same risk wearing four costumes.
The vulnerability is already visible in the receivables. Five customers accounted for 70 percent of Nvidia's accounts receivable at the end of last quarter, up from 56 percent a year earlier, with payment terms stretched from three months to a year for some. Google, one of the hyperscalers underwriting the whole trade, just posted its first negative free cash flow since going public in 2004.
So return to where we started. AA-rated Nvidia, with low debt and record profits, trading like a BBB credit.
The bond market is not confused about Nvidia's earnings. It is pricing the structure — the tail risk that Morgan Stanley flagged as "early stage and difficult to track," migrating through SPVs and private vehicles where disclosure thins out.
Nvidia's real innovation was never the GPU. It was a self-referential risk architecture that lets one balance sheet manufacture demand, book it as revenue, and now buy the developer on-ramp to defend it.
The circle is elegant while it turns. The spread on Nvidia's own bonds is the market's quiet verdict that the circle is the risk.